Opening the book…
Let X1, X2, . . ., Xn be n independent random variables with means µ1, µ2, . . ., µn and variances σ21 , σ22 , . . ., and σ2n . Let Y be a random variable that is a linear combination of Xi with weights ai so that Y = 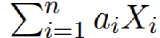 .
As the sum of two Gaussian random variables is again a Gaussian, Y is Gaussian distributed with a mean
\[\mu _{Y}=\sum_{i=1}^{n}a_{i}\mu _{i}\]
and a variance
\[\sigma _{Y}^{2}=\sum_{i=1}^{n}a_{i}^{2}\sigma _{i}^{2}\]
This page titled 15.4: Linear Combinations of Independent Gaussian Random Variables was last modified on Tue, 10 Aug 2021 01:33:39 GMT and is shared under a CC BY-NC 4.0 license and was authored, remixed, and/or curated by Nikolaus Correll via source content that was edited to the style and standards of the LibreTexts platform.
The book could not be loaded just now.